Colorado Restaurant Business Owners Policy

See How We're Different
or call us: 1-800-969-9740
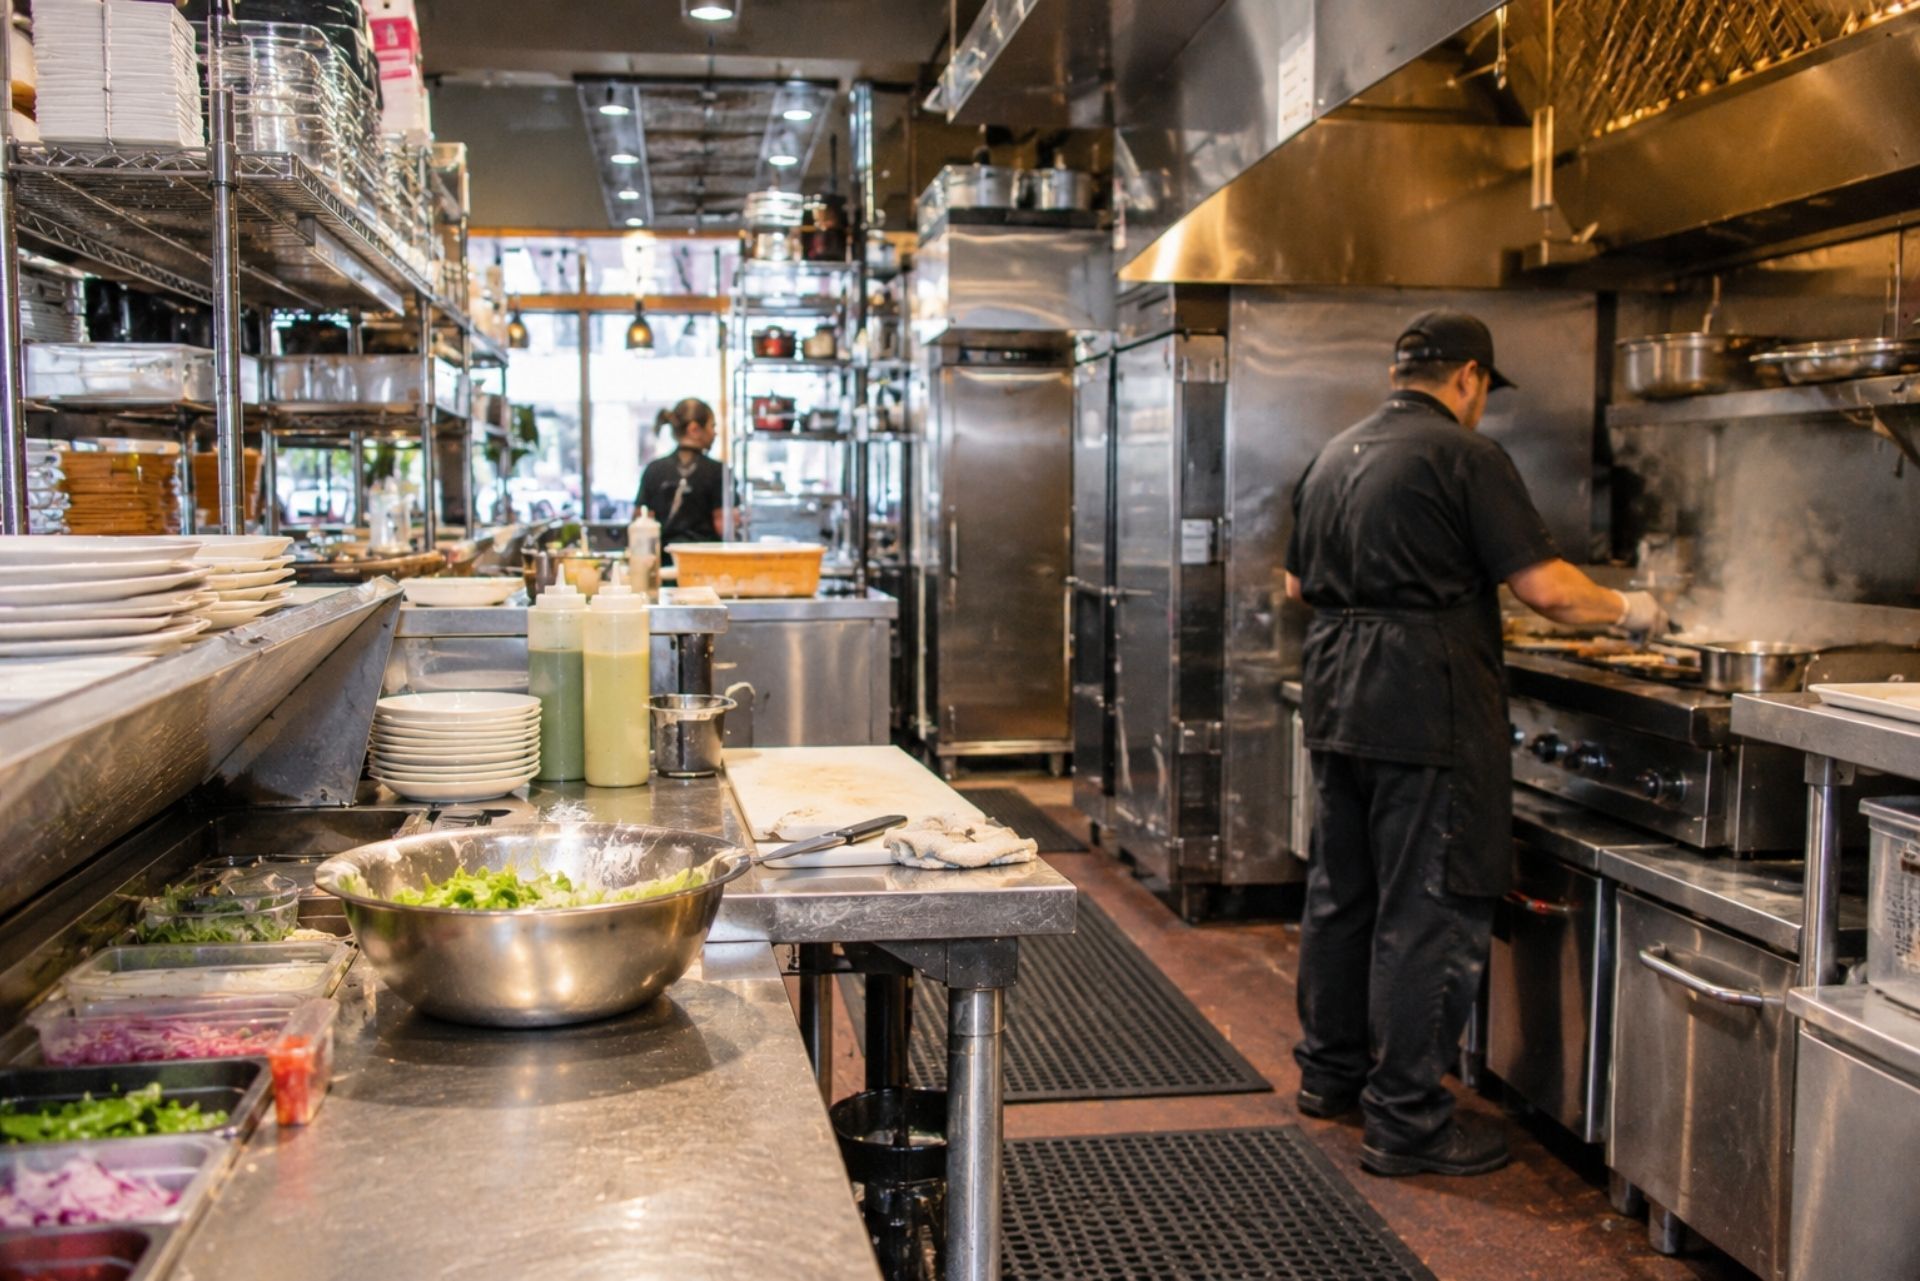
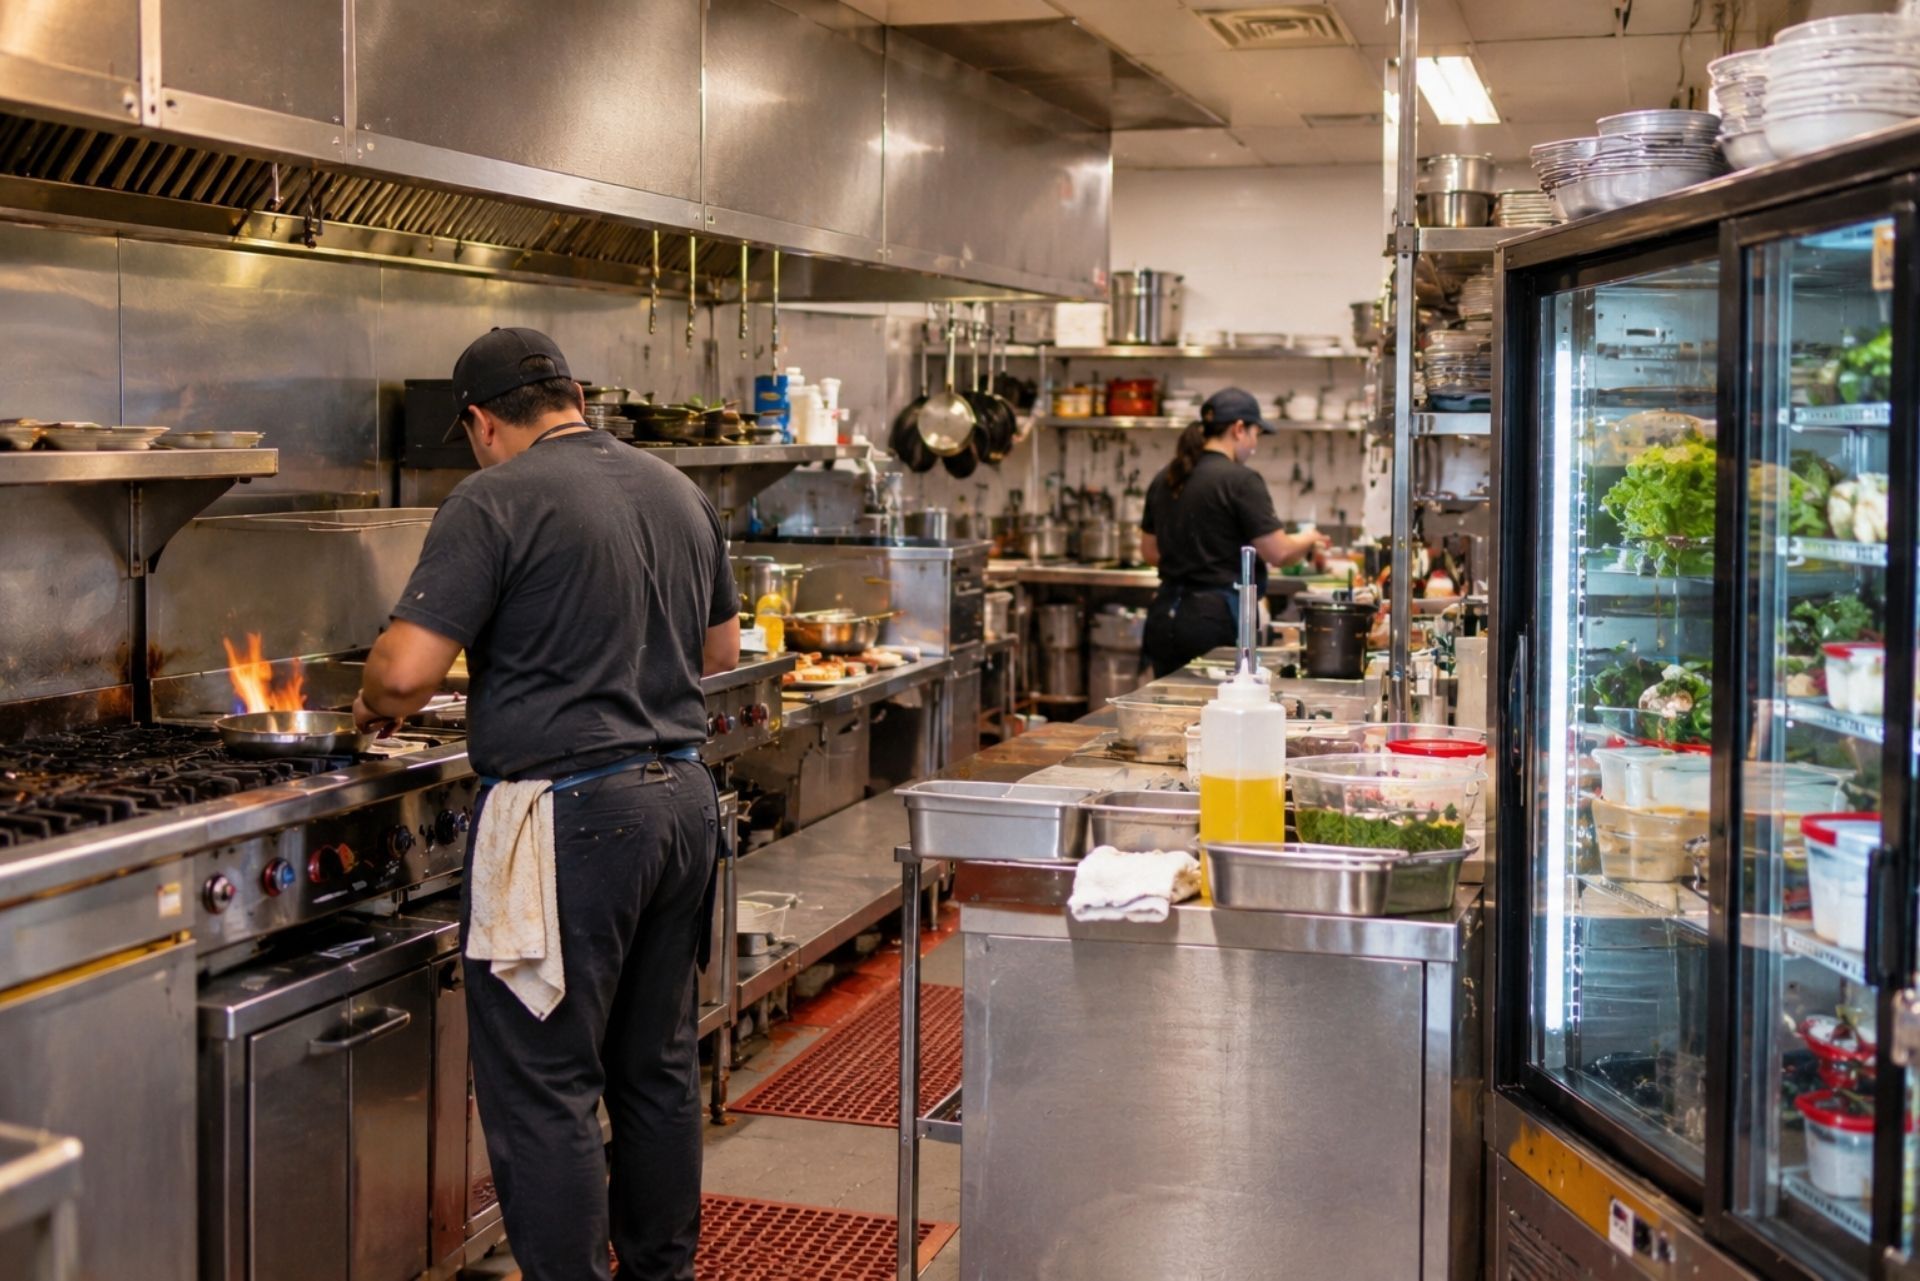
A grease fire that starts at 9 p.m. on a Friday doesn't just burn your hood system. It closes your dining room for six weeks. It ruins $8,000 worth of proteins in the walk-in and sends a line cook's guest to urgent care with smoke inhalation. Each of those losses falls under a different piece of your insurance, and most Colorado restaurant owners don't learn which pieces they're missing until the adjuster calls.
A Business Owners Policy is the foundation most independent restaurants build on. Too many owners buy one off a quote sheet without reading the endorsements, and that's where the trouble starts. In Colorado, the stakes are higher than in most states. Front Range hailstorms shred rooftop condensers, and mountain wildfires knock out power for days. Medical costs push liability claims higher every year.
This guide covers what a Colorado restaurant BOP actually protects, including property,
general liability, equipment breakdown, business income, spoilage, and costs. It also covers where the gaps hide and what you should expect to pay in 2026. A single uncovered claim, like a compressor failure on a holiday weekend, can wipe out a year of profit for a small restaurant.
Understanding Business Owners Policies for Colorado Restaurants
A Business Owners Policy bundles three coverages into one contract: commercial property, general liability, and business income. Carriers package them together because small businesses with similar risk profiles tend to need the same core protection. The bundle is cheaper than buying each line separately, and it simplifies renewals.
Restaurants are a special case. Most carriers have a dedicated restaurant BOP form with industry-specific endorsements, and many carriers set eligibility limits. A quick-service café or a 60-seat bistro usually qualifies. A late-night bar where alcohol makes up more than half of sales often doesn't, and gets pushed into a standalone package policy instead.
Here's what a BOP does not include, no matter how good the carrier is:
- Workers' compensation: Required in Colorado once you have a single employee, and written separately through a private carrier or Pinnacol Assurance
- Liquor liability: Usually a separate policy or a specific endorsement, never automatic
- Commercial auto: Your catering van or delivery car needs its own coverage
- Employment practices liability: Wrongful termination and harassment claims need EPLI
One mistake I see constantly is owners assuming "full coverage" means everything. A BOP is a starting point. You build the rest of your program around it based on how your restaurant actually operates.
By: John R. Thomas
Commercial Lines Director and Managing Partner at Loft & Co Insurance Services
Core Protections: Property and General Liability
These two coverages form the base of every restaurant BOP. Property handles damage to things you own. General liability handles damage you cause to other people.
Safeguarding Your Physical Assets
Commercial property coverage pays to repair or replace your building (if you own it), your tenant improvements, kitchen equipment, furniture, POS systems, and inventory. The key detail on your declarations page is valuation. Replacement cost pays what it takes to buy new equipment today. Actual cash value subtracts depreciation, so a 10-year-old range might pay out a few hundred dollars against a $9,000 replacement.
Colorado property risk is unusual. The state ranks 6th nationally for property insurance costs, driven by a double-peril problem: hail along the Front Range and wildfire in the mountains. If your restaurant sits in Fort Collins, Aurora, or Colorado Springs, expect a separate wind and hail deductible, often written as a percentage of building value rather than a flat dollar amount. A 2% hail deductible on a $1.2 million building means you're covering the first $24,000 yourself.
Mountain town operators face wildfire scoring. Starting October 12, 2026, insurers must disclose the wildfire risk models and scores they use for property premiums. You can appeal those scores and get credit for mitigation work like defensible space and ember-resistant vents. Ask your agent for your score at every renewal.
Managing Third-Party Liability Risks
General liability covers bodily injury and property damage to third parties, plus personal and advertising injury under Coverage B. For restaurants, the classic claims are slip-and-falls near the dish pit or on icy entryways. You'll also see foodborne illness claims, burns from hot plates, and choking incidents. Products-completed operations coverage matters here, since it responds when a guest gets sick after eating your food at home.
Liability rates for Colorado restaurants are running 10% to 22% higher than the national average in 2026, mostly because of rising regional medical and hospital costs. A broken hip from a winter fall at the front door can easily produce a six-figure claim once surgery and lost wages are added.
Most restaurant BOPs carry $1 million per occurrence and $2 million aggregate. If your landlord requires higher limits, or you serve alcohol, an umbrella policy is usually the cheapest way to get there.
Essential Restaurant Endorsements: Spoilage and Equipment Breakdown
Base BOP forms are built for offices and retail shops. Restaurants need add-ons, and these two cause the most claim denials when they're missing.
Protecting Inventory from Power Failures
Spoilage coverage pays for perishable food lost to temperature changes. The catch is where the power failure starts. Standard BOPs often exclude spoilage from off-premises power failures unless a Utility Services - Direct Damage rider is attached.
That distinction matters a lot in Colorado. Xcel Energy and rural electric co-ops now use public safety power shutoffs during high wind and red flag days. When the utility cuts power to your block for 36 hours, that's an off-premises outage. Without the utility services rider, your walk-in full of brisket, dairy, and seafood is your loss to eat.
When you review spoilage coverage, check three things:
- The sublimit, which is often $5,000 to $10,000 by default and too low for a full-service kitchen
- Whether off-premises utility failure is included
- Whether a mechanical breakdown of your own cooler triggers spoilage, or only power loss
Repairing Ovens, Walk-ins, and HVAC Systems
Equipment breakdown covers mechanical and electrical failure, like a burned-out compressor, a shorted control board on a combi oven, or an electrical arc in your panel. Standard property coverage excludes these "internal" failures. It only responds to external causes like fire or theft.
From the claims side, rooftop HVAC and refrigeration condensers generate more trouble than ovens do. Hail damages the fins, the unit runs hot, and the compressor fails weeks later. Without equipment breakdown, the carrier can argue the failure was wear and tear. Make sure the endorsement includes expediting expenses so you can pay for overnight parts and weekend technicians.
Sustaining Cash Flow with Business Income Coverage
Business income insurance replaces lost net profit and pays continuing expenses like rent, loan payments, and payroll while you're shut down after a covered loss. It doesn't stand alone. A covered property claim has to cause the closure first, which is why a pandemic or a bad review won't trigger it.
The detail that trips owners up is the waiting period. Most 2026 Colorado BOPs include a 72-hour waiting period before business income kicks in. Close for three days after a kitchen fire and you get nothing for those days. If your Friday and Saturday dinner service produces $14,000 in profit, that waiting period effectively works like a $14,000 deductible. Some carriers will buy the waiting period down to 24 hours for a modest premium, and for a high-volume weekend restaurant, that's usually worth it.
Watch for these related provisions:
- Extended period of indemnity: Pays after you reopen while customers trickle back, often 60 days standard and extendable to 180 or more
- Civil authority: Covers closures ordered by officials when a nearby covered loss blocks access, like a wildfire evacuation
- Dependent property: Responds when a key supplier suffers a loss and can't deliver
Business income limits should be based on 12 months of numbers, not a guess. Pull your P&L, and have your agent run a worksheet. Underinsuring here leads to coinsurance penalties that cut your payout.
Comparison of Standard vs. Enhanced BOP Coverage
Not every restaurant BOP is built the same. Here's how a bare-bones form compares with a restaurant-specific enhanced form.
| Coverage Feature | Standard BOP | Enhanced Restaurant BOP |
|---|---|---|
| Property valuation | Often actual cash value | Replacement cost |
| Food spoilage | Low sublimit or none | $10,000 to $50,000+, includes off-site power loss |
| Equipment breakdown | Excluded | Included, with expediting costs |
| Business income waiting period | 72 hours | Can be reduced to 24 hours |
| Extended indemnity | 30 to 60 days | 180+ days available |
| Utility services rider | Not included | Included or available |
| Hail deductible | Percentage-based | Flat dollar options sometimes available |
| Food contamination | Not included | Covers health department closures and cleanup |
The enhanced version costs more, often a few hundred dollars a year. That premium is small compared with a single uncovered compressor failure on a summer weekend. Food contamination coverage deserves extra attention, because a health department closure after an outbreak creates zero property damage and gets no response from standard business income.
Factors Influencing Insurance Costs in Colorado
A standard BOP for a small-to-mid-sized Colorado restaurant typically runs $2,000 to $3,500 per year in 2026. Where you land in that range, or above it, depends on factors you can partly control.
Location drives the property side. A strip-center café in a Front Range hail corridor pays more than a similar spot in Grand Junction. A log-construction restaurant in a wildland-urban interface area pays more than both. Construction type, roof age, and sprinkler status all move the needle.
Operations drive liability pricing. Carriers look closely at:
- Cooking methods: Open flame, deep fryers, and solid-fuel ovens raise rates
- Fire suppression: A UL 300-compliant hood system with documented semiannual inspections earns credits
- Alcohol sales percentage: Higher liquor ratios push premiums up or move you off the BOP entirely
- Hours: Late-night service correlates with more liability claims
- Claims history: Two slip-and-fall claims in three years will cost you at renewal
Compliance issues can create indirect exposure too. Since January 1, 2026, Colorado law bans hidden fees and mandatory service charges that aren't built into the menu price. Restaurants that refuse refunds face actual damages plus 18% interest compounded annually. Your BOP won't cover these regulatory penalties, so clean up your menu pricing now.
If private carriers turn you down, the Colorado FAIR Plan is
fully operational as an insurer of last resort for businesses denied by at least three private carriers. Expect narrower coverage and higher prices, so treat it as a bridge rather than a long-term answer.
Common Questions About Colorado Restaurant Insurance
Do I need a BOP if my landlord already has building insurance? Yes. Your landlord's policy covers their building, not your equipment, inventory, improvements, or liability to guests. Most leases require you to carry your own BOP and name the landlord as an additional insured.
Does my BOP cover me if a customer gets food poisoning? General liability typically covers the guest's injury claim. Your lost income during a health department closure usually needs a separate food contamination endorsement.
What happens at my annual audit? Some carriers audit sales or payroll after the policy year ends. If your revenue came in higher than estimated, you'll owe additional premium, so report growth to your agent mid-year rather than getting a surprise bill.
How fast do I need to report a claim? Report as soon as possible, ideally within 24 to 48 hours. Late notice gives the carrier grounds to dispute coverage, especially on spoilage claims where evidence gets thrown away.
Will a hail claim raise my premium? It can, but weather claims usually affect pricing less than liability claims, since carriers rate hail by territory. Repeated roof claims on an aging roof can lead to non-renewal.
Can I lower my wildfire-related premium? Under Colorado's 2026 disclosure rules, you can request your wildfire score and appeal it. Documented mitigation work, like clearing vegetation and installing ember-resistant vents, can earn premium credits.
Making the Right Choice for Your Restaurant
A strong restaurant insurance program starts with a BOP that fits how you actually cook, serve, and operate. Get replacement cost valuation on your equipment. Add equipment breakdown and a spoilage endorsement with a utility services rider, because Colorado power shutoffs aren't rare anymore. Base your business income limits on real financials, and think hard about buying down that 72-hour waiting period.
Work with an agent who writes restaurants every week, not a generalist who quotes them twice a year. A specialist knows which carriers handle hood fire claims fairly and which ones flag fryers. They also know which forms include food contamination. Shop your coverage every year against at least three carriers, and compare forms, not just premiums.
Before your next renewal, pull your declarations page and check it against the comparison table above. Every "no" on that list is a claim waiting to be denied. Close those gaps now, while it costs a few hundred dollars instead of your whole season.
About The Author:
John R. Thomas
As Commercial Lines Director and Managing Partner at Loft & Co Insurance Services, I specialize in crafting strategic insurance solutions for businesses—especially contractors, real estate owners, logistics firms, and industry-specific operations. With years of experience in risk management and policy design, I’m committed to delivering clarity, value, and protection that helps you focus on growth.
Contact Us
Risk Management from Real Experts With You in Charge
Professional Policies Designed For Your Business.
Enjoy tailored insurance and risk management solutions customized to your industry and business size.
Colorado Commercial Insurance Blog
Contact Us
Phone
Location
Denver
5990 Greenwood Plaza Blvd, Ste 270
Greenwood Village, CO 80111
Des Moines
130 E 3rd St. Ste 201
Des Moines, IA 50309